Born and raised in Orange County. Still reading these properties every week.
We specialize in California, particularly Southern California, while offering financing options across 30+ states. Local knowledge is not a slogan here — it is how a scenario gets read.
We describe property and financing considerations. We do not publish local market forecasts.
Coverage across 30+ statesA property reads differently when you have watched the neighborhood.
Southern California investment property spans an unusually wide range: 1950s beach-adjacent bungalows, 1970s stucco fourplexes, newer infill townhomes, and small commercial buildings on arterial streets. Each carries its own financing logic.
Our background combines appraisal, financing, and real estate. That means we ask what supports the value before we ask what the payment is — and we ask what the payment does to your cash flow before recommending a structure.
We do not operate an office in every city where we arrange financing, and we do not claim to. What we do have is a lifetime of local property context and lending partners that reach beyond California.
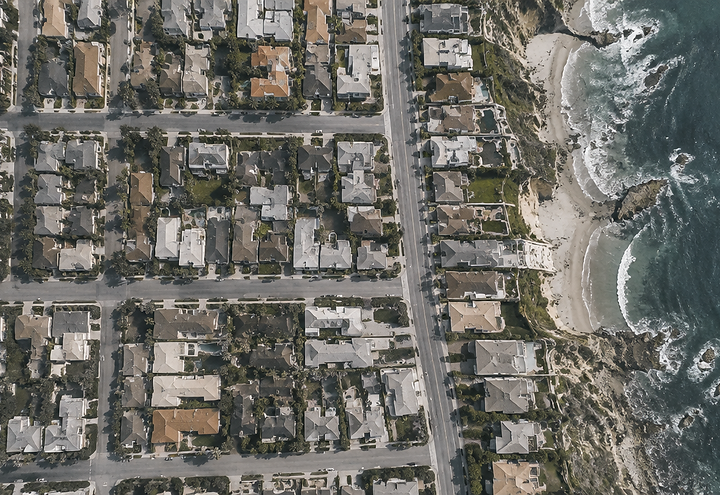
Property types we evaluate most often
Coastal single-family rentals
Higher basis, tighter cash flow, and a buyer pool that values condition and location over yield. Rent support and exit value often tell different stories.
Small multifamily, 2 to 4 units
Unit mix, separate metering, and deferred maintenance drive both income and the appraisal. A two-unit with one below-market lease reads very differently than a stabilized fourplex.
Dated bungalows and flips
Older housing stock means scope-of-work discipline matters more than the purchase price. Permits and structural surprises are the usual overruns.
Infill land and small commercial
Entitlement risk, utility access, and use restrictions determine what the parcel can support. Land is financed more conservatively than improved property.
Five questions, in order.
These apply anywhere, but they matter most where land is expensive and housing stock is old.
Property type
What the unit actually is matters — condominium versus single-family, attached versus detached, legal versus non-conforming units. Lenders treat these differently, and so does the resale market.
Rental economics
We look at achievable rent, not aspirational rent: current leases, comparable rentals, vacancy patterns, and the operating costs that come with older housing stock.
Acquisition strategy
Whether you are buying at market, buying distressed, or acquiring a tenant-occupied property changes the financing, the timing, and the reserve you should carry.
Renovation plans
A cosmetic refresh and a structural renovation are different projects. Scope, permits, and a realistic schedule drive both the budget and the draw structure.
Exit considerations
Selling, refinancing, or holding all require a different answer to the same question: what does this property look like in three to five years, and who buys it then?
Tell us about the property. We will tell you how it reads.
Send the address, the plan, and the numbers. We will review the scenario with Southern California context and confirm what may be available.
Illustrative tools and scenario review only. Not a rate quote, pre-approval, or commitment to lend.